


Ada Aquino
Branch Manager | nmls#988589
908-956-7152 | Office & Fax
732-762-7069 | Cell
[email protected]
Building Equity
• Renting vs. Buying
• Appreciation
• Obtainability
Our Products
Do’s & Dont’s⚬
Do’s & Dont’s⚬
Do’s & Dont’s⚬
Do’s & Dont’s⚬
Do’s & Dont’s⚬
Do:
• Provide photocopies of all requested documents in a timely fashion.
• Ask to be informed.
• Keep files current with the most recent copies of your pay stubs and bank statements
• Continue to make all payments on credit cards, loans and or rental or mortgage accounts as agreed apon.
• Maintain a paperwork trail of every thing connected to your application
• Let us know if you need to make a large deposit
• Let us know BEFORE anyone runs your credit.
Don’t:
• Apply or take out new credit cards, auto or personal loans or have new inquiries in your credit bureau file.
• Make any large, unverifiable and un-documented deposits or withdrawals to your checking or savings.
• Quit or change employment.
• Write any insufficient funds checks.
• Take any cash advances out on credit cards to pay for your escrow deposit.
• Withhold payment to accounts to be paid off in closing without first discussing it with your Personal Mortgage Advisor.
• Dispute any items on your credit report.
• File any lawsuits or change marital status.
Pre-approved
“Move to the front of the line.”
It’s always a good idea to get pre-approved for a mortgage before you start shopping for a home. Realtors and sellers often give priority to pre-approved buyers, so it can help you get to the front of the line. Plus, being pre-approved gives you a better idea of how much house you can afford.
Meet with a Realtor
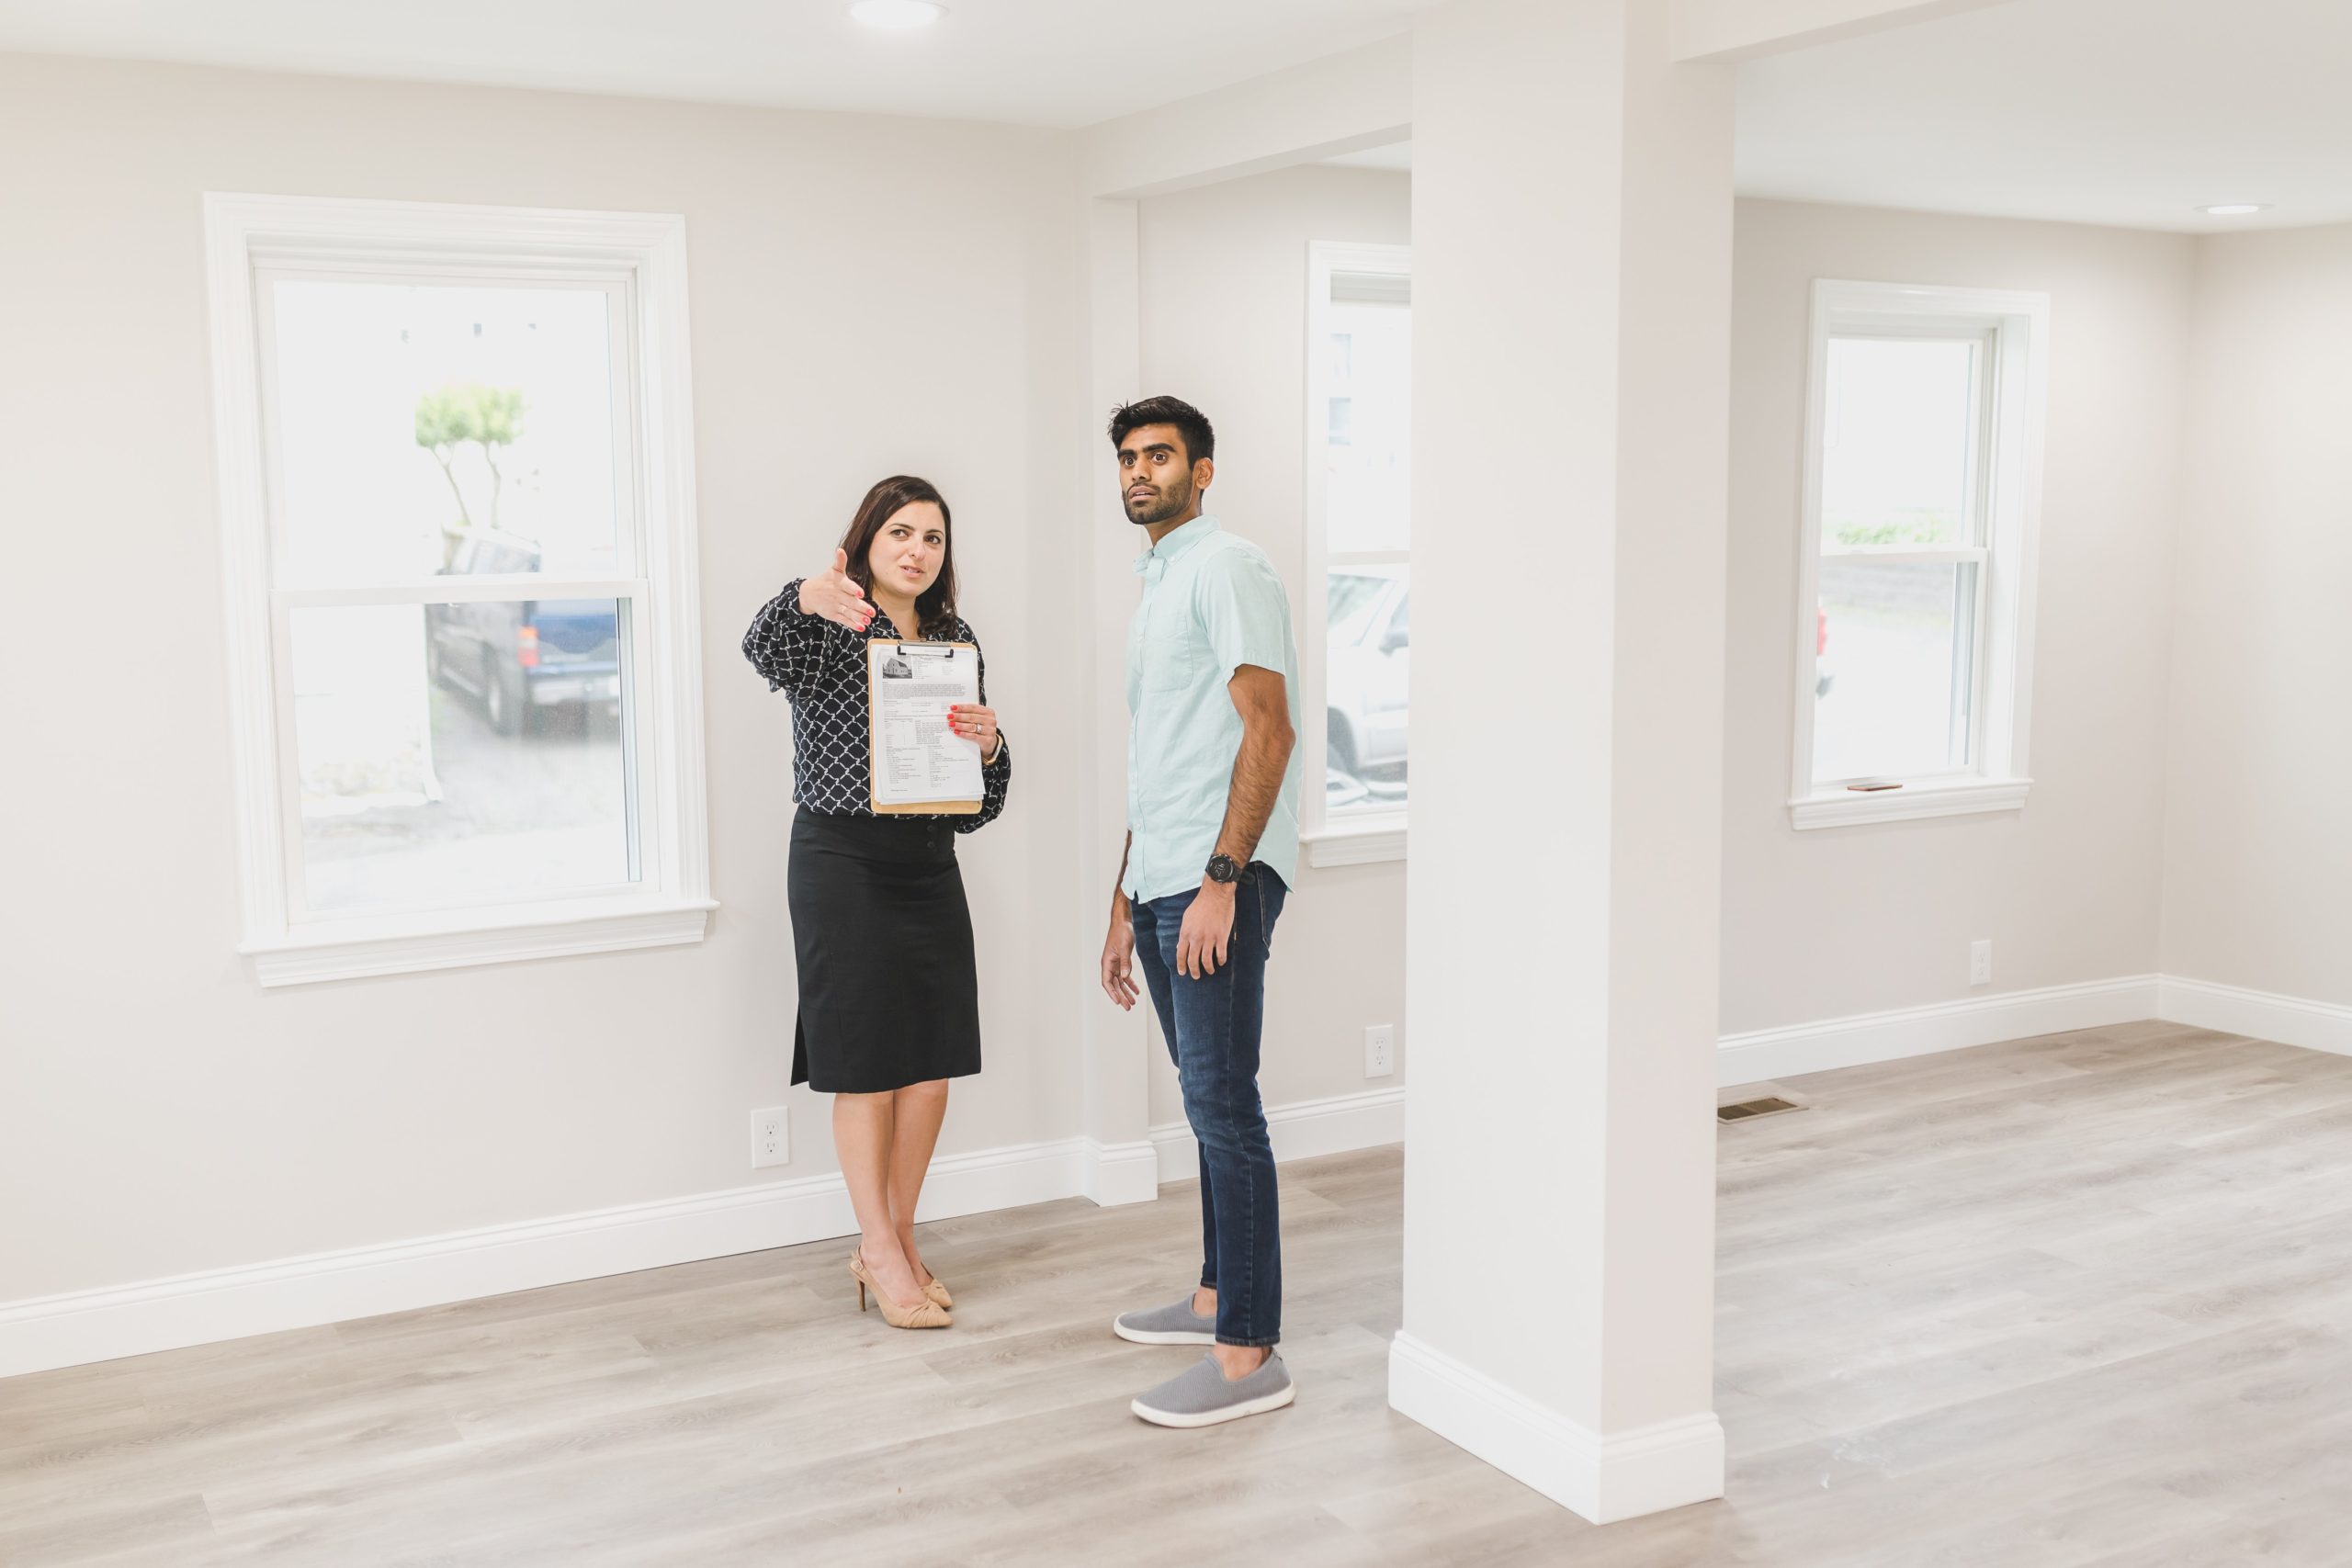
A real estate agent is a licensed professional who arranges real estate transactions, putting buyers and sellers together and acting as their representative in negotiations.
• Interview your real estate agents options
• Initial meeting: wants, needs, and timeline
• MLS search begins
• Schedule showings with your real estate agent
• Make an offer!
Under Contract
A buyer’s offer on a home has been accepted by the seller, but the sale is not yet final.
- Celebrate!
- Deposit your *Earnest Money
- Schedule your inspection
- Provide your lender and/or real estate agent any requested documents in a timely manner
*Funds provided to the seller, held in escrow, and then applied to the remaining down payment balance upon closing.
Money Needed for Home Purchase
- General Inspection – ~$400-$500
- Radon – ~$150
- Sewer Scope – ~$190
- Appraisal – ~$600-$700
- Specialist – can vary
Loan Estimate and Disclosures
A loan estimate and disclosure sent will be sent to you as the borrower, you must then perform “Intent to Proceed”.
Inspection
Limited non-invasive examination of the condition of a property. Written report of finding is provided to buyer to make informed decision about pending transaction.
• Go to the inspection
• Ask questions
• Review the report
• Walk through the report with your real estate agent
• Draft an objection (if applicable)
• Come to a resolution
Appraisal
• Confirm your lender has ordered/scheduled
• Give your lender the *green light* after the Inspection
• Review the report
• Walk through the report with your real estate agent
• Renegotiate purchase price (if applicable)
• Come to a resolution
